
Bitumen
Weekly Bitumen Report: Peace Message from Washington, War Threats Before the US Elections
Global bitumen prices remain under pressure from geopolitical tensions, tight supply, and rising shipping costs. While Asian markets show mixed trends, Iran faces growing export risks as transport restrictions and uncertain delivery routes complicate trade.
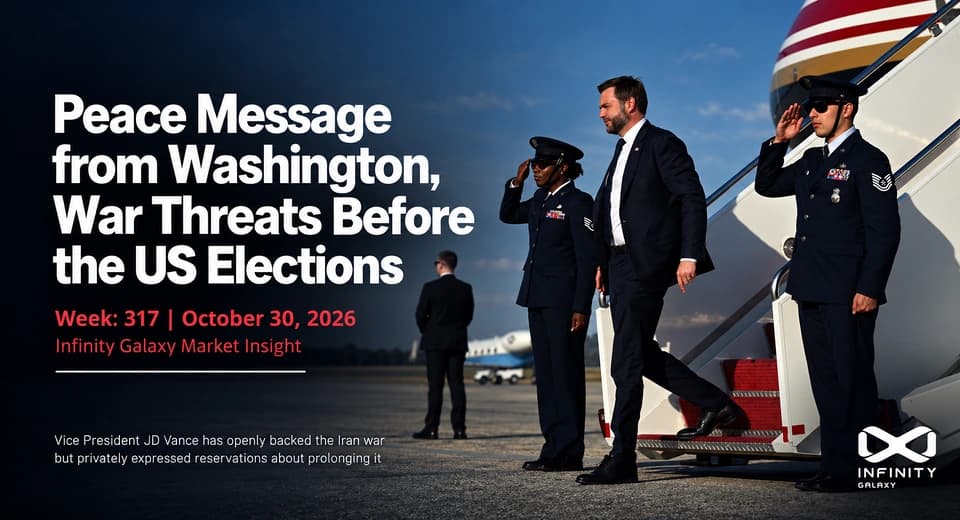
The final week of October brought a significant development in relations between Iran and the United States. Reports indicated that US Vice President JD Vance had sent a letter to Mohsen Rezaei to explore the possibility of resuming negotiations.
Meanwhile, Qatar, supported by Pakistan, proposed a seven-day framework for confidence-building measures and ending the war, although Tehran rejected parts of the proposal as unacceptable. Visits and discussions involving senior officials from Saudi Arabia, Pakistan, and Turkey in Tehran, alongside Qatar's continued mediation efforts, suggest that diplomatic attempts to prevent further escalation are ongoing. However, disagreements over Iran's nuclear program, the lifting of oil sanctions, and the blockade of Iranian ports remain unresolved.
In contrast to these diplomatic developments, Israel held its parliamentary elections on October 27, while the United States approaches its November 3 midterm elections. At the same time, reports emerged about possible renewed military strikes against Iran, while the Houthis claimed to have targeted a refinery in Saudi Arabia. Continued fighting in Yemen, threats of potential disruption to undersea communication cables in the Persian Gulf, and concerns over further restrictions in the Strait of Hormuz indicate that the risks of war now extend beyond oil.
Maritime security, telecommunications infrastructure, and international trade are also under pressure. The extent of damage from recent attacks and whether further threats will materialize remain uncertain.
Europe's economic situation has also become more complicated. Social protests in France, rising living costs, government debt pressures, and concerns over interest rates have affected investment prospects and infrastructure projects, contributing to broader social unrest across Europe.
Brent Crude Oil: Retreating from Recent Highs as Diplomacy Eases Part of the War Risk
After climbing above $115 per barrel on Wednesday, October 28, Brent crude retreated on Thursday following fresh reports about possible negotiations between Iran and the United States. Early Thursday trading reports placed Brent at around $114 per barrel. This volatility shows how quickly traders react to diplomatic developments while continuing to price in the risk of potential oil supply disruptions.
The main drivers behind last week's oil price rally were growing concerns over the security of Saudi energy facilities, the Strait of Hormuz, and the possibility of further military escalation. A decline of approximately 1.9 million barrels in US crude oil inventories also supported prices, although rising gasoline inventories and the prospect of improved Russian refinery output partially offset the upward pressure. The recent rally therefore appears to have been driven more by geopolitical risk and potential supply constraints than by a significant increase in global oil demand.
Singapore and South Korea Bitumen: Supply Remains Tight, but Buyers Are Becoming More Cautious
Singapore's bitumen market maintained its upward trend from previous weeks, with FOB prices reaching $848/MT, an increase of $6/MT week on week. Limited access to suitable refinery feedstock and restricted availability of export cargoes continued to support prices.
South Korea followed a different trend. Export bitumen prices declined to $812/MT FOB, mainly reflecting weaker demand from China as colder weather began affecting construction activity in parts of the country.
India Bitumen: Import Prices Rise as the Market Awaits Further Refinery Adjustments
India's bitumen market remains under pressure from rising supply costs following repeated refinery price increases in recent months. Four rounds of price adjustments were recorded during September and October, at the beginning and middle of each month. The latest mid-October increase amounted to approximately $75/MT for VG30 and $85/MT for VG40.
Import prices also continued to rise. On October 27, Platts assessed CFR prices for VG30 and VG40 bitumen on India's west coast at $690/MT and $695/MT, respectively, while east coast assessments reached $730/MT and $735/MT. These figures represented increases of $50/MT compared with the October 20 assessments.
Despite the resumption of road construction activities following the monsoon season, elevated prices and contractors' liquidity constraints continue to make buyers cautious. Higher refinery prices therefore do not necessarily indicate proportional growth in consumption. Supply schedules and the ability to deliver imported cargoes have become increasingly important in purchasing decisions.
China Bitumen: Domestic Prices Fall While Singapore Remains Firm
While Singapore faces tight supply and elevated prices, China's bitumen market has entered a correction phase.
The decline was particularly pronounced in the domestic market. South China bitumen prices fell to $858-873/MT, with the weekly average decreasing by $67/MT. East China domestic prices also declined by approximately $25/MT. Weaker seasonal demand, the approaching winter, and increased domestic supply were the main factors behind the correction.
Europe and Mediterranean Bitumen: Prices Rise Despite Weak Demand
Europe's bitumen market recorded a second consecutive week of price increases, with prices reaching approximately $620-645/MT. However, higher outright prices and transportation costs have discouraged buyers, while bitumen differentials to high-sulfur fuel oil (HSFO) have weakened at several export ports.
Bahrain's bitumen export price remained around $550/MT FOB. Despite significant oil price volatility and rising bitumen prices in other regions, maritime shipping restrictions and difficult trading conditions in the Persian Gulf have continued to limit changes in this assessment.
Iran Bitumen: Growing Export Pressure from the Strait of Hormuz to Transit Ports
Iran's bitumen market experienced a notable increase in price pressure during the past week. At the same time, tighter restrictions at regional transit ports created additional uncertainty and increased export risks.
Transportation remains the main challenge for Iranian bitumen exporters. Restricted vessel movements through the Strait of Hormuz, threats of maritime attacks, shipping sanctions, and uncertainty over connecting vessel schedules have made contract execution increasingly important relative to the product price itself.
New restrictions at Oman's Sohar Port have added another layer of complexity to export logistics.
Despite these constraints, road and rail exports continue to maintain part of Iran's international trade flows.
Iranian exporters now face more than pricing pressure. They must simultaneously manage shipping routes, vessel availability, delivery schedules, and payment collection risks. Even in markets where demand exists, these challenges can make it difficult to convert a sales quotation into an executable contract.
Insight by Razieh Gilani from Infinity Galaxy
Bitumen prices have increased across most global markets, but the rally is not yet supported by sufficiently strong underlying demand. Singapore continues to face tight supply, India is dealing with higher procurement costs, and Europe remains under pressure from refinery constraints.
For Iran, the situation has become even more complicated. In today's bitumen trade, competitive pricing still matters, but the ability to arrange reliable transportation, secure payment, and deliver cargo on time ultimately determines the real value of a contract.
Comments
Share your thoughts...
More Reports
Curious to see more, discover more articles, and stay up-to-date?