Bitumen
Weekly Bitumen Report: Democratic Tsunami in the US: Oil Plunges 9%. What Happens to the War?
A sharp drop in oil prices following the US midterm elections has reshaped global market expectations. However, weaker Asian demand, rising Indian refinery prices, and shipping disruptions continue to drive diverging trends across bitumen markets.
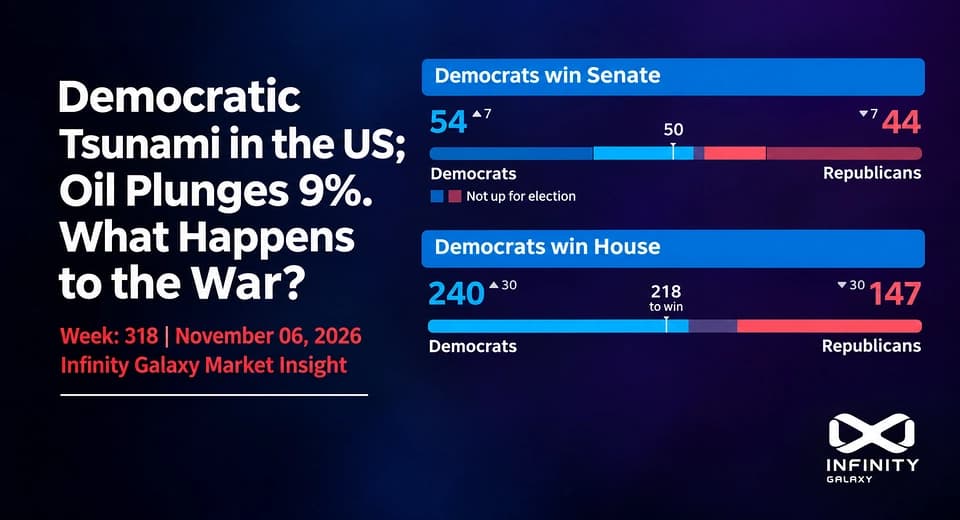
The Democrats' sweeping victory in the November 3 US midterm elections, securing control of both the House of Representatives and the Senate, was the week's most significant political development. After months of war with Iran, the result represents a major political setback for Donald Trump and the Republicans. Rising living costs, pressure from high energy prices, and public dissatisfaction with the prolonged war contributed to this political shift.
JD Vance also acknowledged the impact of the Iran war on the Republican defeat, having previously stated that Trump does not want a prolonged conflict with Iran. The election outcome could increase political pressure to resume negotiations, although a change in congressional control does not necessarily mean an immediate end to the war.
Meanwhile, Qatar's mediation efforts to bring Tehran and Washington closer continue, but fundamental disagreements remain unresolved. Despite these diplomatic developments, reports of new tanker incidents in the Strait of Hormuz, a US attack on Qeshm Island, continued maritime insecurity, and the worsening crisis in Yemen indicate that the risks of war have not disappeared from global trade.
Threats around the Bab el-Mandeb Strait have also raised concerns about alternative shipping routes. In reality, markets face two conflicting developments: the possibility of political de-escalation and the persistence of disruptions to maritime transportation.
Brent Crude Oil: From $118 to $93 in One Week. Is War Risk Fading, or Are Market Expectations Changing?
Brent crude, which climbed to approximately $118 per barrel on October 30, entered a downward trend following signs of a possible easing of tensions between Iran and the United States. The decline accelerated after the US midterm election results, with Brent falling 8.7% on November 4 to close at around $94 per barrel. In early trading on November 5, prices approached $93, representing a decline of nearly 21% from the previous week's peak.
The main driver of this decline was a shift in traders' expectations regarding the future of the war and the possibility of easing oil supply restrictions in the Persian Gulf. At the same time, weaker manufacturing data from China raised additional concerns about future oil demand. However, maritime restrictions and supply disruptions have not yet been fully resolved. The recent decline therefore reflects a reduction in the geopolitical risk premium rather than a confirmed return to normal market conditions.
Singapore and South Korea Bitumen: Singapore's First Decline Since July, with a Sharper Fall in South Korea
After several months of rising prices, Singapore's bitumen market recorded its first correction since July. On November 4, Singapore bitumen was assessed at approximately $845/MT. Weaker demand from Southeast Asian buyers, sufficient inventories among some importers, and competitive offers from Malaysia and China were the main factors behind this change.
Downward pressure was stronger in South Korea, where export bitumen prices fell to approximately $770/MT, around $45/MT lower than the previous week.
Despite the decline in crude oil and high-sulfur fuel oil (HSFO) prices, Singapore continues to face supply constraints. Further price corrections therefore remain possible.
India Bitumen: Fifth Refinery Price Increase as the Market Moves Against Falling Oil Prices
India's bitumen market experienced another refinery price increase at the beginning of November. According to an industry announcement, Indian refiners raised VG30 prices by approximately $13/MT and VG40 prices by around $15/MT, effective November 1. This marked the fifth round of price increases since early September, occurring just as global oil prices entered a sharp downward trend.
Import prices also remained above the previous week's levels. On November 3, Platts assessed CFR prices for VG30 and VG40 bitumen on India's west coast at $695/MT and $700/MT, respectively, while east coast assessments reached $745/MT and $750/MT.
China Bitumen: Economic Weakness, Slowing Demand, and Growing Export Competition
In China, economic developments have placed additional pressure on the global demand outlook. The country's official manufacturing Purchasing Managers' Index (PMI) declined in October, returning to contraction territory. Weak domestic consumption, fewer new orders, and concerns over exports have reinforced expectations of further pressure on China's economy.
China remains one of the main sources of downward pressure on East Asian bitumen prices.
According to international market assessments, imported bitumen prices in East China fell to $790-810/MT CFR, with the weekly average declining by $5/MT. Domestic prices in eastern and southern China also came under pressure from weakening demand.
Europe and Mediterranean Bitumen: Prices Rise Despite Falling Oil and Weak Demand
Unlike East Asia, Europe's bitumen market remained on an upward trend during the week ending October 30. Mediterranean export prices reached approximately $650-675/MT.
Refinery production constraints across Europe, combined with short-term demand ahead of winter, continued to tighten supply in several markets.
Bahrain's bitumen price remained unchanged at approximately $550/MT FOB.
Iran Bitumen: Export Prices Rise, but Shipping Restrictions Continue to Deepen
Despite higher bitumen prices this week, Iran faced a further decline in export activity due to shipping restrictions in the Persian Gulf.
The main factors behind the price increases were higher vacuum bottom (VB) feedstock costs, limited supply, and difficulties in executing export shipments. However, higher prices did not necessarily translate into stronger actual sales.
Maritime transportation remains the primary obstacle to Iranian exports, with restrictions on vessel movements through the Strait of Hormuz continuing to disrupt shipments. In addition, new restrictions at Oman's Sohar Port on import and re-export procedures have placed further pressure on one of the operational routes used by exporters.
Road and rail exports have continued to maintain part of Iran's trade flows. However, their capacity to replace maritime shipments remains limited, while higher logistics costs reduce the competitiveness of Iranian suppliers in many destinations.
Insight by Razieh Gilani, from Infinity Galaxy
The Democrats' victory in the United States and the sharp decline in oil prices have changed expectations across global energy markets, but the underlying supply chain challenges remain unresolved. East Asia faces weaker demand and declining prices, while Europe and Iran continue to struggle with supply and transportation constraints. India, meanwhile, has introduced another refinery price increase despite the downward trend in crude oil.
For Iranian exporters, a reduction in political risk can only become a genuine commercial opportunity when shipping routes, payment collection, and cargo delivery capabilities also improve. Otherwise, falling oil prices may put additional pressure on profit margins before export costs begin to decline.
Comments
Share your thoughts...
More Reports
Curious to see more, discover more articles, and stay up-to-date?