
East Asia Bitumen Market
East Asia Bitumen Market: Rail Trade to China Grows, A New Route for Regional Bitumen Trade
East Asia bitumen markets move in different directions as Singapore and Thailand prices rise while South Korea eases. Higher freight costs, weak Chinese demand and growing rail trade to China are reshaping regional competition and buying decisions.
Regional Overview | Brent Near $110/bbl, Singapore Strengthens, Korea Softens and Rail-to-China Gains Traction
Brent crude approached $110/bbl amid security risks in the Strait of Hormuz and rising marine fuel costs, increasing pressure on regional logistics and freight. This week, prices diverged across origins, with Singapore and Thailand strengthening, South Korea correcting lower, and China's domestic demand remaining weak. Buyers increasingly focused on delivered costs, availability and execution reliability rather than FOB prices alone.
SINGAPORE | Prices Rise Amid Tight Supply
FOB prices increased to $844–854/MT, approximately $12/MT higher week-on-week. November availability remained limited, with some offers reaching $880/MT. Vietnamese buyers assessed levels around $855/MT, while Indonesian demand remained largely focused below $800/MT. Purchasing activity continued to be driven mainly by urgent requirements.
MALAYSIA | Demand Improves, Affordability Remains a Concern
Demand strengthened to moderate-to-strong, supported by projects targeting year-end completion. However, higher transportation costs from Singapore continued to pressure project economics, keeping buyers focused on domestic supply where available.
INDONESIA | Buyers Remain Price-Sensitive
Most buyers continued targeting Singapore-origin bitumen below $800/MT FOB, although urgent buyers were willing to negotiate at $845/MT and above. The gap between immediate demand and price-sensitive buyers widened further.
THAILAND | Prices Continue Upward
November offers stood around $850/MT FOB or higher, with buying indications near $835/MT. Prices rose approximately $15/MT week-on-week. Improving weather could support road-repair demand, although the pace of recovery remains uncertain.
VIETNAM | Buyers Compare Competing Origins
November-loading Singapore cargoes were assessed around $900/MT CFR South Vietnam, while offers stood at $920–940/MT CFR. Thai cargoes were discussed at $900–920/MT CFR, and South China and Taiwan material around $880/MT CFR Haiphong. High prices continued to encourage buyers to compare origins based on total delivered cost.
SOUTH KOREA | Competitiveness Improves
FOB prices eased to $813–824/MT, with November-loading transactions reported around $810–820/MT. The correction improved Korea's relative competitiveness, subject to grade availability and loading schedules.
CHINA | Domestic Demand Softens
The expected post-holiday recovery failed to materialize, and buyers continued purchasing mainly for immediate needs. East China import bids eased to around $850/MT CFR, while South China November offers stood at $830–855/MT FOB, keeping the region competitive as an alternative export origin.
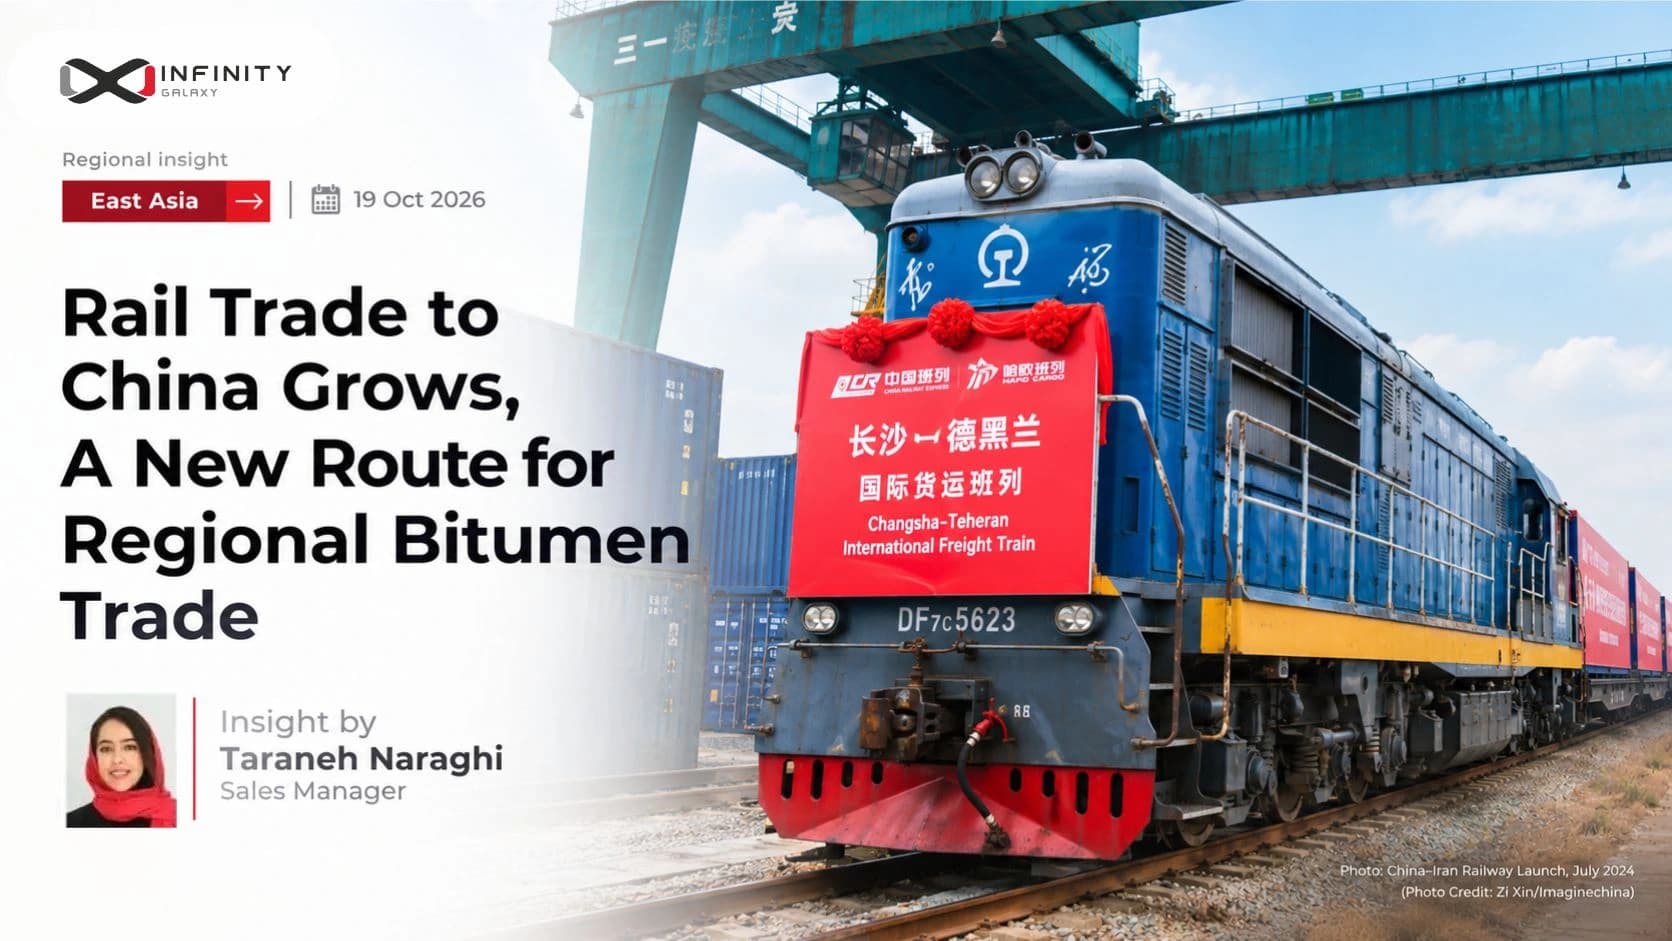
CIS & CENTRAL ASIA | Rail-to-China Activity Gains Attention
Uzbekistan transactions were reported around $375–385/MT ex-factory. A key development was the reported active rail export of jumbo bags to China, with border-point cargoes discussed around $370–385/MT FOB/FCA.
Although this confirms activity on regional rail routes to China, the specific origin of these cargoes remains unconfirmed. Iranian and Iraqi bitumen in one-tonne jumbo bags packed inside steel cages remains an offering option for CIS and Central Asian destinations, subject to route feasibility and logistics arrangements.
If you need more information about rail-to-China activity read Iran to China Rail Freight for Bitumen via Aprin Dry Port article.
East Asia Market Insight by Taraneh Naraghi
This week highlighted growing differences in origin competitiveness:
- Singapore and Thailand: Higher prices supported by tight supply.
- Malaysia and Indonesia: Demand increasingly constrained by affordability.
- Vietnam: Stronger focus on comparing delivered costs across origins.
- South Korea: Improved competitiveness following a price correction.
- China: Softer domestic demand, with South China remaining a viable export alternative.
- Rail-to-China: Reported jumbo-bag rail activity provides a stronger basis for evaluating regional rail opportunities.
For Infinity Galaxy, the priority is to assess each opportunity through the combined impact of origin, grade, availability, freight, route and execution reliability.
The lowest FOB price is not necessarily the best deal; the strongest opportunity is the cargo offering the most competitive and reliable overall delivered economics.
Comments
Share your thoughts...
More Reports
Curious to see more, discover more articles, and stay up-to-date?