Africa Bitumen Market: Prices Are Calmer, but Supply Routes Have Not Normalized Yet
Africa’s bitumen market is calmer, but shipping constraints still shape buying decisions. Iranian cargo remains attractive on FOB terms, while October demand and changing supply may make availability, freight and delivery certainty more important.
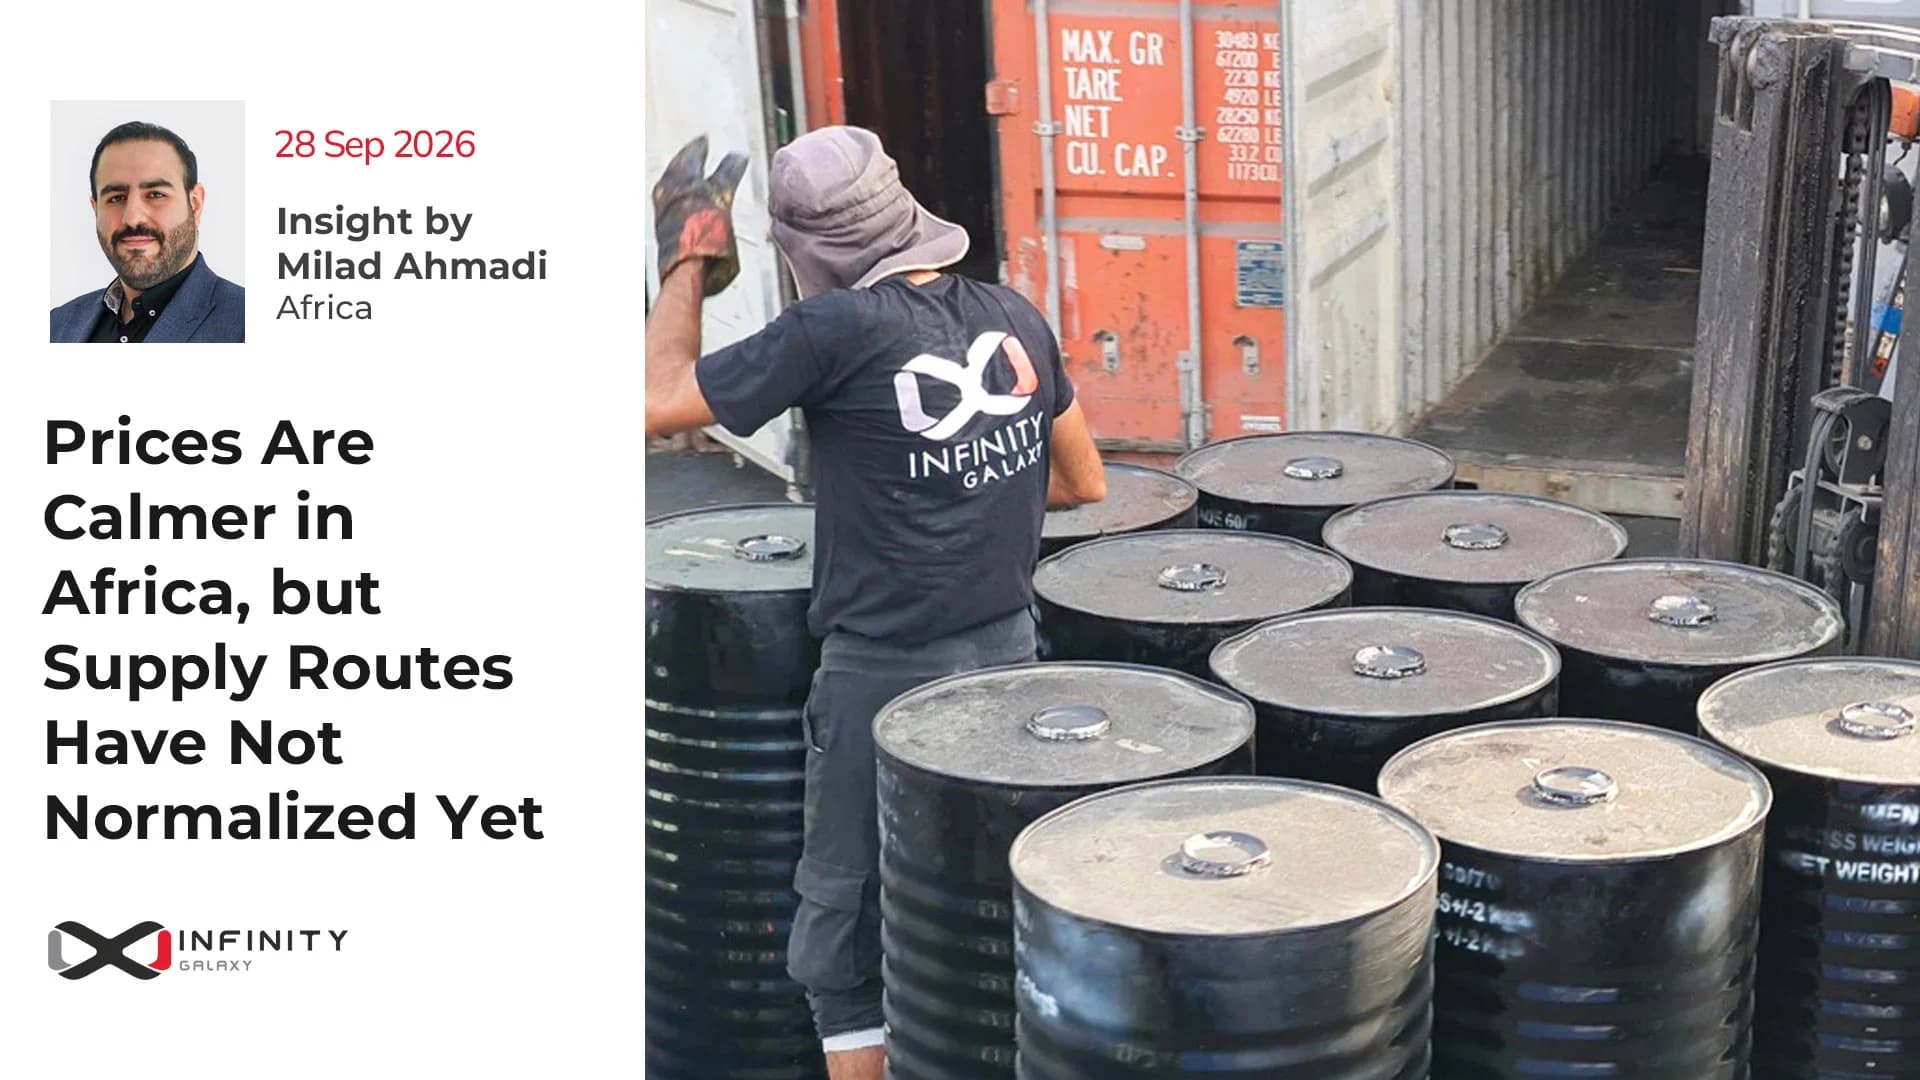
The African bitumen market has become calmer compared with the sharp volatility seen earlier in September, but shipping constraints from the Middle East Gulf continue to influence purchasing decisions across Africa.
Market discussions increasingly show buyers distinguishing between a low price on paper and a cargo that can actually be executed and delivered.
This is particularly visible in East Africa, where Iranian bitumen remains attractive on an FOB basis, while direct shipping routes are still operationally difficult for many transactions.
Nigeria: Prices Relatively Stable, Buyers Waiting for October
CFR Lagos levels have moved only slightly higher than last week, with the market now well away from the sharp increases seen earlier in September.
Some Nigerian buyers built significant inventories during August and therefore do not currently have an urgent need for new cargo. At the same time, with the dry season approaching in October, consumption and truck loading are expected to increase again.
Production limitations in Abidjan have also reduced part of the traditional supply flow into Nigeria, encouraging some buyers and traders to look more closely at Mediterranean cargoes.
Market View:
Nigeria is currently not a panic-buying market. For buyers with October requirements, confirmed arrival, available volume and loading schedule are more important than rushing to secure the first offer available.
Ghana & Ivory Coast: Limited Supply Today, Potential Improvement in October
In Ivory Coast, production limitations in Abidjan continue to affect export availability, restricting both seaborne flows and land-based supply to surrounding markets.
However, an important change may be approaching. The arrival of new feedstock into Abidjan could improve production availability during October.
In Ghana, demand has strengthened in recent weeks, while a cargo from Greece has arrived in Tema. This shows that the market is becoming less dependent on regional supply, with alternative origins playing a larger role.
Market View:
For Ghana and Ivory Coast, buyers should not focus only on today's price. October availability could change the negotiation equation, making purchasing timing increasingly important.
Cameroon & West Africa: Part-Cargo Remains a Practical Option
Part-cargo flows from the Mediterranean into West Africa continue. One cargo from Spain is scheduled to discharge part of its volume in Douala before continuing toward Nigeria.
This model remains a practical option for buyers who do not require a full cargo.
Market View:
For Cameroon and similar markets, defining the volume, discharge port and delivery window from the beginning can improve the chances of finding a suitable part-cargo opportunity.
Burkina Faso: Coastal Availability Remains Critical
The Burkina Faso market remains dependent on land-based supply from Ivory Coast. As a result, any disruption or improvement in Abidjan availability can directly affect the ability to supply this market.
Market View:
For landlocked markets, FOB price alone is not an adequate benchmark. Border movement, truck availability and actual loading capability are equally important parts of the transaction.
Kenya & East Africa: Iranian Bitumen Is Cheaper, but Execution Is More Difficult
Across East Africa, suppliers continue to actively look for cargoes from Greece, Turkey and South China.
The reason is straightforward. Although Iranian offers remain around the low-$300s/MT FOB, shipping from the Middle East Gulf remains logistically difficult for many transactions.
Freight for drummed cargo from Bandar Abbas/Jebel Ali to Mombasa and Dar es Salaam also remains around $275–290/MT.
Market View:
In East Africa, the lowest FOB is not necessarily the most competitive CFR. Buyers need to evaluate origin, freight, shipping availability, payment route and loading confirmation together.
Kenya, Uganda, DRC & South Sudan: Demand Is Strengthening
Cargo imported from Turkey into Mombasa has effectively entered the market, and current supply in Kenya is largely supporting demand through existing trucking flows.
At the same time, Uganda, DRC and South Sudan are showing stronger demand expectations for October, while Burundi continues to receive relatively stable land-based supply.
Market View:
For inland East Africa, actual stock in Mombasa is more valuable than a low but uncertain offer. As October approaches, prompt availability may become increasingly important.
South Africa: Supply Remains High, but Demand Is Returning
South Africa has entered spring and paving activity is gradually increasing. Demand typically accelerates from October and reaches stronger levels during the summer months.
At the same time, several additional cargoes are expected to arrive in South Africa over the coming weeks, meaning supply currently appears sufficient.
Import activity through Durban is also noticeably higher than during the same period last year.
Market View:
South Africa is not currently facing a shortage, so buyers still have room to negotiate. However, as seasonal demand increases, this balance could change during October. ETA and prompt stock should be checked before making a purchasing decision.
Africa Market Summary by Milad Ahmadi
This week, the African bitumen market is less about price movements and more about changing availability.
West Africa: Prices have become relatively calmer, but supply limitations from some regional origins remain, while October could bring better availability.
East Africa: Iranian bitumen remains attractive on an FOB basis, but logistics are pushing buyers toward Mediterranean and Asian origins.
Southern Africa: Cargo availability remains healthy, while seasonal demand is gradually returning.
The Key Message This Week
The cheapest FOB is not always the cheapest executable deal.
In the current market, the real value of an offer depends on:
Available Cargo + Origin + Freight + Loading Window + Payment Route + Delivery Certainty
Planning Your Next Bitumen Shipment?
A competitive FOB price is only the starting point. The real question is whether the cargo can be shipped and delivered within your required timeframe, under workable payment and logistics terms.
If you are planning a shipment to Africa for October or the coming months, send me a direct message with your destination country, bitumen grade, packing preference, approximate volume and required delivery window.
At Infinity Galaxy, I can help assess the available origins and shipping routes against your requirements, so you can compare workable delivered options rather than FOB prices alone.
Comments
Share your thoughts...
More Reports
Curious to see more, discover more articles, and stay up-to-date?