Weekly Bitumen Report: This Week, from the Hormuz Strait to the Red Sea Under Pressure; Asian Bitumen Prices Rise by Up to $50/MT
Asian bitumen prices rose by up to $50/MT this week as Hormuz and Red Sea risks tightened supply and shipping. India moved sharply higher, while Europe stayed more balanced and Iran remained competitive despite difficult freight conditions.
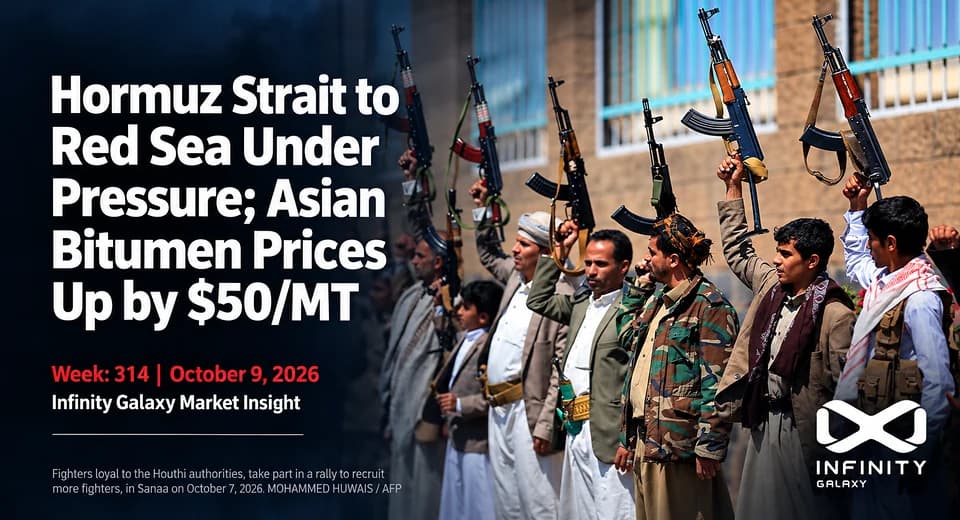
The energy market entered another new phase this week. Yemen’s Houthis intensified their attacks on Saudi Arabia over the past few days, targeting two airports, and on the morning of October 8, the group also claimed responsibility for a missile attack on another airport in Riyadh. At the same time, Saudi Arabia expanded its operations in Yemen, bringing Bab el-Mandeb back into the energy security equation, as part of Saudi oil exports move through the Red Sea to bypass disruptions in the Hormuz Strait.
On the other side of the region, the Hormuz Strait has not become calmer either. In the week ending October 5, at least 12 attacks, attempted attacks, or reported incidents involving oil tankers were recorded- the highest weekly number since the war began. New data also showed that only seven container ships crossed the Hormuz Strait on October 6, while oil flows through the strait fell to around 10 million barrels per day, or roughly 74% of pre-war levels. In the same high-risk environment, Washington has asked the Pentagon to prepare possible options for renewed military operations against Iran, but no final decision or specific timetable has been announced. For the market, the more immediate issue remains restricted transit, shipping availability, and insurance costs.
This combination has kept Brent crude above the $100 per barrel level. On the morning of October 8, Brent rose by more than 2% to around $102-103 per barrel. On one side, the market is watching higher Middle East exports and plans to accelerate the release of IEA oil reserves. On the other, tanker attacks, declining US crude inventories, and the risk of production disruption in the Gulf of Mexico continue to prevent the supply-risk premium from disappearing.
East Asia Bitumen: Bitumen and Fuel Oil Rise Together, but Tight Supply Remains the Main Story
In East Asia, fuel oil strengthened alongside bitumen this week. Singapore HSFO 180 CST was assessed at around $737 per metric ton, while Singapore bitumen reached around $795 per metric ton. South Korean bitumen also increased to around $780 per metric ton. Both markets have gained by roughly $40 per metric ton, showing that limited supply remains a stronger driver than short-term movements in crude oil.
China: Holiday Demand Slowed Temporarily, but Fuel Export Restrictions Added More Pressure to the Asian Market
China’s Golden Week holiday from October 1 to 7 temporarily slowed domestic bitumen consumption. At the same time, Beijing’s decision to halt petroleum product exports in October to destinations outside Hong Kong and Macau tightened the regional energy market. Lower Chinese fuel flows into Singapore have contributed to declining inventories. This matters directly for Singapore and South Korea because it keeps fuel oil and feedstock costs at elevated levels.
India: After the Early-October Price Shock, the Market Is Still Absorbing Higher Levels
India remains one of the most important bitumen markets this week. Argus indicates that bitumen prices are around $50 per metric ton higher than the previous week. With the post-monsoon season underway and Diwali approaching, demand is still expected to strengthen. However, high freight costs and delays affecting vessels operating in the region continue to keep some buyers cautious.
Europe and Bahrain: Europe Moves Higher but Still Trades Well Below Asia
Europe remains more balanced than East Asia, although prices are no longer completely stable. Comparable export levels across Europe are currently in the range of approximately $560-585 per metric ton, while stronger HSFO has pushed truck prices higher in several European markets.
Bahrain, meanwhile, remains unchanged at around $550 per metric ton, while export activity stays very weak because of restrictions affecting vessel movements through the Hormuz Strait.
Iran: Attractive Prices, but Shipping Still Determines Whether a Deal Is Workable
In Iran, higher feedstock costs and limited supply continue to support prices, but current regional conditions remain the main obstacle to trade. The large price gap between Iran and Asian markets therefore does not automatically translate into an easy transaction. Still, for buyers with an executable shipping route, Iran remains one of the most competitively priced origins in the market.
Insight from Razieh Gilani at Infinity Galaxy: In a Fast Market, a Price Without Certainty Has a Short Life
When oil can move by two dollars within hours, freight changes with every security development, and the price gap between Iran and Asia reaches several hundred dollars per metric ton, a “good price” is no longer simply the lowest number. An offer has real value when the seller is available, knows the actual volume that can be supplied, understands the shipping route, and responds quickly when the market moves. In this environment, trust is no longer an additional advantage; it has become part of the transaction itself.
Comments
Share your thoughts...
More Reports
Curious to see more, discover more articles, and stay up-to-date?