

Africa Bitumen Market
Africa Bitumen Market : Demand Is Returning, but Supply Origins Are Shifting
As Africa's road paving season nears, bitumen demand is picking up. However, restrictions on Mideast Gulf shipments are pushing buyers toward European cargoes, raising freight costs and replacement expenses across key regional hubs.
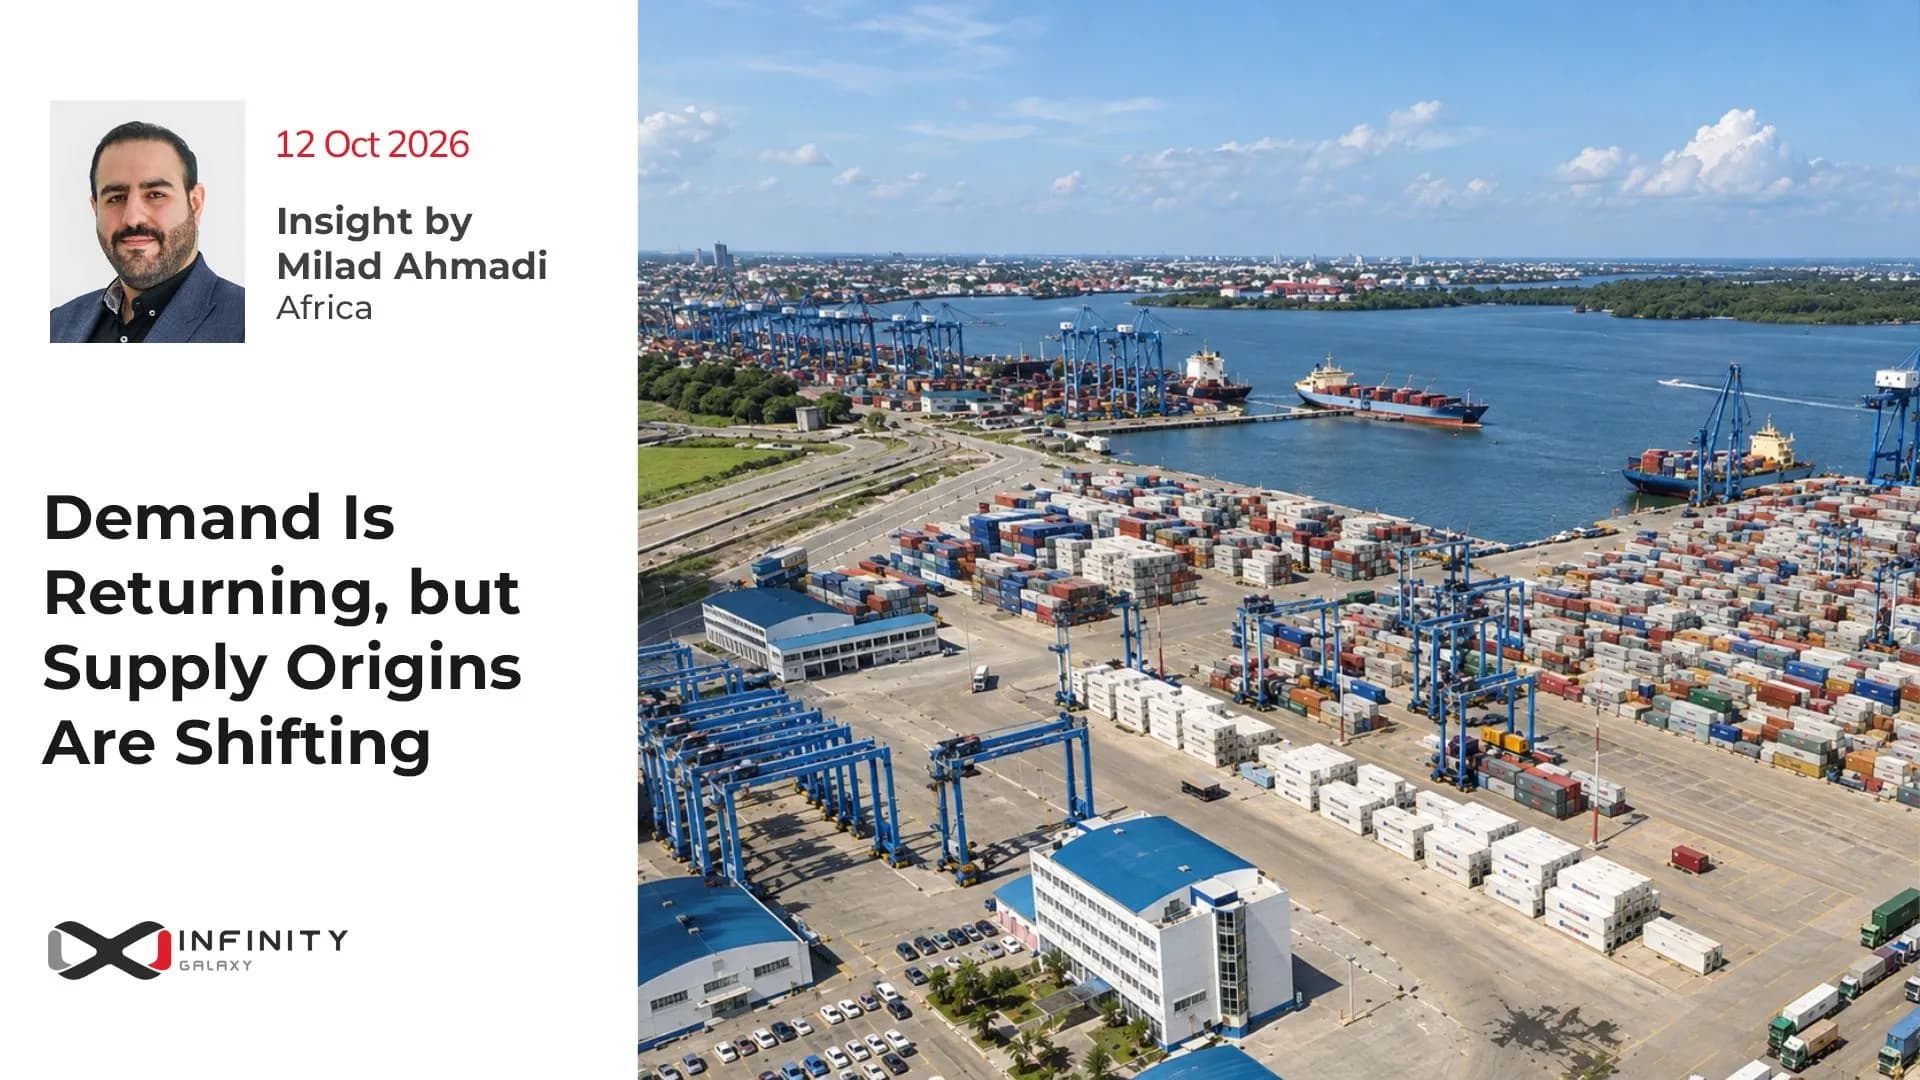
As many African markets approach the more active road paving season, demand is gradually picking up. However, in East and Southern Africa, continued restrictions affecting Iranian supply and shipments from the Mideast Gulf are prompting buyers and importers to look more closely at European and Mediterranean cargoes.
The result is straightforward: supply remains available, but along certain routes, it comes with higher replacement costs and freight expenses.
Nigeria: Dry-Season Demand Is Returning
Market assessments indicate that CFR Lagos prices edged higher this week, with negotiable offers generally ranging from the mid-$760s to the low-$770s/MT CFR.
However, the more significant change is in buyer behavior. As the dry season approaches, end-users and importers are already looking to secure volumes for October and the following weeks.
At the same time, supply is no longer dependent on a single origin. New cargoes from Mediterranean suppliers and regional hubs are moving toward Nigeria.
Market View
The Nigerian market is no longer simply in wait-and-see mode, as it was several weeks ago. With confirmed cargo, a clear ETA and workable payment terms, buying activity is likely to become more active during October.
Ghana & Ivory Coast: Supply Is Recovering, but Conditions Have Not Fully Normalized
Production in Abidjan is gradually recovering toward more normal levels following restrictions over the past several months. This could improve availability for Ivory Coast and neighboring markets.
However, the effects of earlier supply constraints are still being felt, and some Ghanaian inventories had fallen to lower levels by the end of September.
CFR Ghana prices also edged higher this week, while cargo flows from Mediterranean origins and West African hubs continue.
Market View
Conditions in Ghana and Ivory Coast have improved compared with last month, but buyers still need to distinguish between anticipated supply and cargo available today. A confirmed loading window remains more valuable than an indicative offer without firm shipment details.
Senegal, Cameroon & Gabon: Regional Cargo Flows Remain Active
Large cargoes from Turkey and other Mediterranean origins continue moving toward West Africa, with some volumes distributed across several regional markets through ship-to-ship (STS) transfers or part-cargo arrangements.
This supply model continues to offer practical options for destinations such as Senegal, Cameroon and Gabon, particularly for buyers who do not require a full cargo.
Market View
In these markets, identifying a suitable part-cargo becomes easier when volume, packaging and delivery period are clearly defined from the outset.
Kenya & Tanzania: Stable Headline Prices, Higher Real Supply Costs
CFR prices for drummed bitumen in Mombasa and Dar es Salaam remained broadly stable compared with the previous week. However, this stability does not tell the whole market story.
East African suppliers continue to look beyond the Mideast Gulf, seeking cargoes from Europe and the Eastern Mediterranean. These alternatives are operationally viable, but their costs are higher than those of the region's traditional supply routes.
Meanwhile, freight for drummed cargoes from Bandar Abbas/Jebel Ali to East Africa remains elevated, at approximately $315–340/MT.
Iranian FOB prices remain competitive on paper, with bulk offers in the low-$300s/MT and drummed material around $400/MT FOB. However, shipping restrictions and sanctions-related constraints continue to limit practical access to these prices.
Market View
For Kenya and Tanzania, the key question is no longer simply:
Which origin offers the lowest FOB price?
The more important question is:Which cargo can actually be loaded, shipped, paid for and delivered?
Kenya, Uganda & DRC: Strong Demand, with Europe Helping Fill the Supply Gap
Bitumen demand in Kenya and inland markets remains strong, and available imported supply is being absorbed quickly.
A new European cargo is being planned for arrival in Mombasa in early November, while the market is also discussing further shipments for November and December.
Truck movements to Uganda, the Democratic Republic of the Congo (DRC) and South Sudan remain active.
Market View
For buyers in these markets, prompt stock or confirmed inbound cargo is more valuable than a cheaper offer with uncertain execution. Under current demand conditions, delivery timing can directly affect the commercial outcome of a transaction.
Burundi & Sudan: Inquiries Continue, but Route Risks Differ
Market discussions also point to new requirements emerging from Burundi and Sudan.
Burundi can still be served through established East African supply networks. Sudan, however, presents greater concerns regarding security and the feasibility of overland transportation.
Market View
In these markets, route feasibility should be assessed before pricing. If a route is unsafe or cannot be executed reliably, a lower origin price offers little practical commercial advantage.
South Africa: Demand Is Rising, but Current Inventories Remain Adequate
South Africa is gradually entering the early summer paving season, and consumption is beginning to increase.
At the same time, several cargoes from European and Mediterranean origins have arrived or remain en route, leaving inventories reasonably well positioned to cover initial seasonal requirements.
An important development is the sharp reduction in traditional supply flows from the Mideast Gulf. As a result, importers are becoming more dependent on higher-cost European cargoes.
Market View
South Africa is not currently facing an immediate shortage, but the replacement cost of new supply has increased. Buyers still retain negotiating leverage, particularly when dealing with prompt cargoes. However, this balance could shift as demand strengthens further into the summer season.
Africa Bitumen Market Summary
This week's market is defined less by a single price movement and more by a shift in supply origins.
• West Africa:The approaching dry season is bringing demand back, while regional availability is gradually improving.
• East Africa: Demand remains strong, but restrictions affecting the Mideast Gulf are increasing the role of European and Mediterranean supply and pushing landed costs higher.
• Southern Africa: Seasonal demand is growing, although current inventories continue to give buyers room to negotiate.
The Key Message This Week
Supply is available, but not always from the origins buyers have traditionally relied on.
In the current market, every offer should be assessed against six key factors:
Origin + Available Cargo + Freight + Loading Window + Payment Route + Delivery Certainty
Planning Your Next Bitumen Shipment?
A competitive FOB price is only the starting point. The real question is whether the cargo can be shipped and delivered within your required timeframe, under workable payment and logistics terms.
If you are planning a shipment to an African destination, send me a direct message with your destination country, preferred packaging, approximate volume and required delivery window.
At Infinity Galaxy, I can help assess which origins and shipping routes are genuinely workable and commercially negotiable under current market conditions.
Milad Ahmadi
Africa Market Specialist-Infinity Galaxy
Comments
Share your thoughts...
More Reports
Curious to see more, discover more reports, and stay up-to-date?

Africa Bitumen Market
Africa Bitumen Market: Sharp Drop in West African Prices Amid Rising East African Costs
The international bitumen market experienced a significant price correction this week following a sharp decline in crude oil and High Sulphur Fuel Oil (HSFO) prices. However, the impact of this correction has not been uniform across Africa. While West African markets have recorded substantial price declines, buyers in East Africa continue to face higher delivered...
Milad Ahmadi
Nov 9, 2026
Africa Bitumen Market
Africa Bitumen Market : Buyers Face Higher Costs and Uncertain Delivery Routes
Prices Are Rising, but Supply Routes Have Yet to Normalize Ongoing tensions between Iran and the United States in the Middle East, restrictions on transit through the Strait of Hormuz, and rising crude oil and marine fuel costs continue to affect bitumen prices and the execution of supply transactions. At the same time, demand is...
Milad Ahmadi
Oct 26, 2026